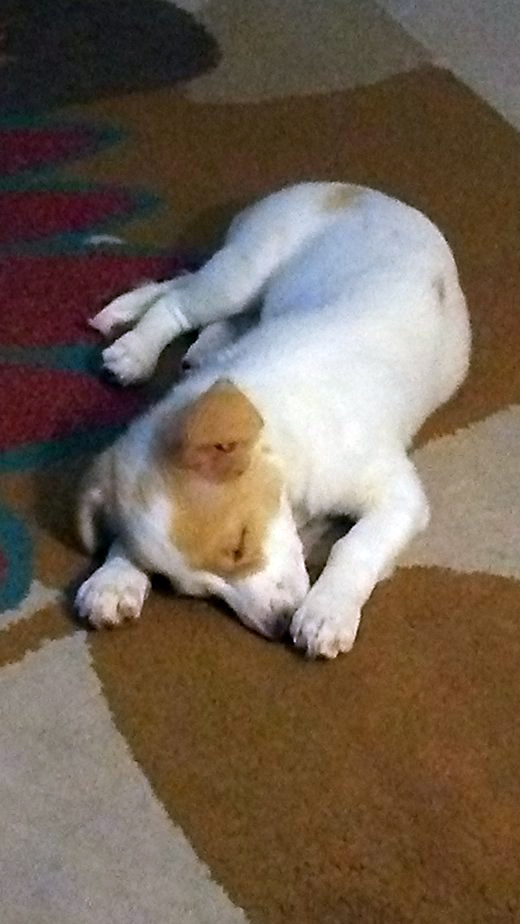
When my lovable little dog, Dapple, needed surgery for a bladder stone, the vet bill topped $4,100. Painful, but not catastrophic, since I'd had pet insurance on her since day one. I thought I'd just send in the receipts and get reimbursed.
Wrong.
CuteCo (not its real name) stalled for months, demanded endless paperwork, and finally offered me $412. So I hauled them into Small Claims Court.
The hearing was held in a cramped conference room. On one side sat the judge, stern in a Puritan-collared suit. On the other: me, clutching receipts and emails, and a claims adjuster CuteCo had flown down to Palm Springs from Seattle. She admitted my policy was valid, but argued CuteCo only had to cover the operation—not anesthesia, exams, or follow-ups. Worse, she contended my deductible was $1,000, not $100.
"What? Look at the Declaration Page," I said, pointing. "It's right there in black and white!"
"Ah," she replied, producing a one-paragraph rider. "You forgot about your endorsement."
And there it was: the fine print from last year's renewal, when I'd clicked a check box for a higher deductible to save a few bucks on premiums.
Oops.
In the end, we settled for a little over $1,000. I left with my receipts, my dented pride, and a new appreciation for an old saying: a lawyer who represents himself has a fool for a client.
Dapple, meanwhile, just wanted dinner.